Black-Scholes and Monte Carlo
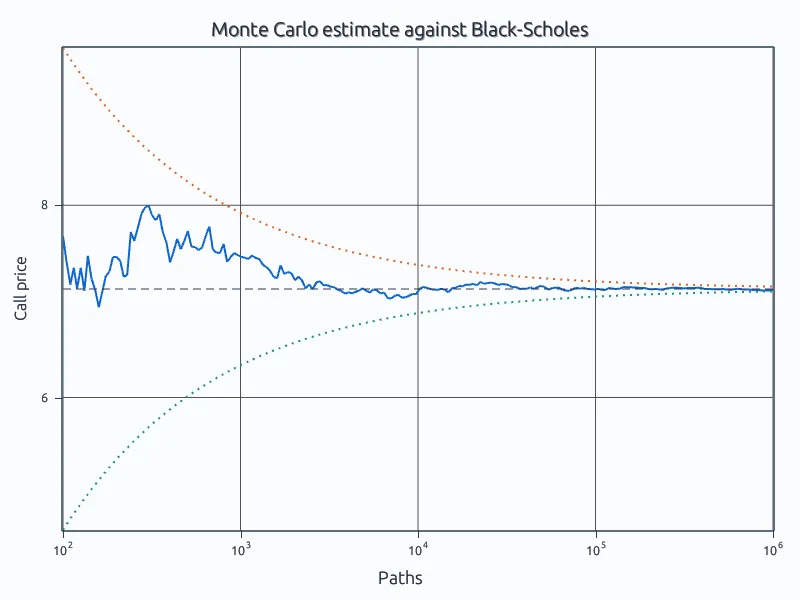
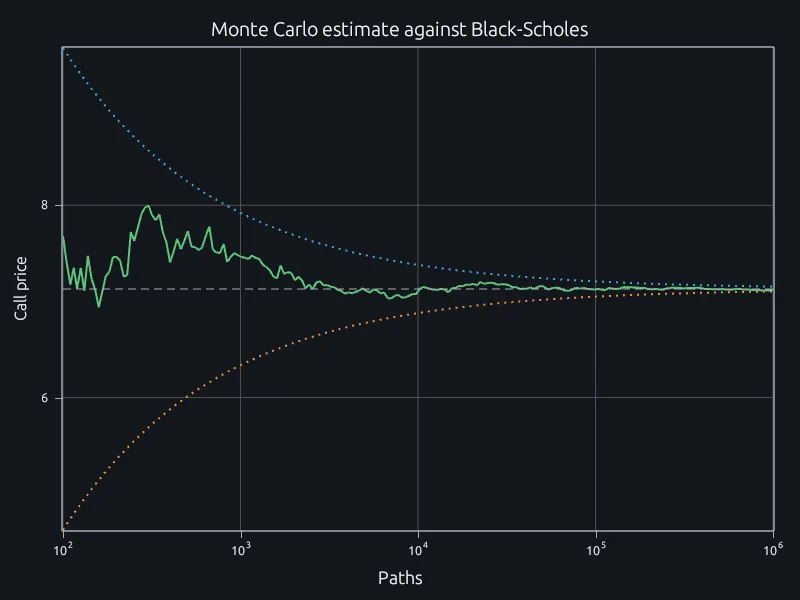
A European call by simulation, inside its standard error of blsprice.
Price options, compute the Greeks, build portfolios and measure risk with blsprice, blsimpv, randn, cov, prctile and the other finance functions you already know.
Pricing options with blsprice and blsimpv usually means paying for a finance toolbox and the toolboxes it depends on. blsprice, blsimpv, macd and the business-day calendar are part of the RunMat runtime, next to randn, cov and prctile.
RuntimePath counts are usually set by how long a run can take. randn, cumsum, exp and mean run on the GPU when the arrays are large, so the same few lines of array code push far more paths through and print a smaller standard error.
GPUA Monte Carlo pricer with a bug can still return a plausible number. Price by simulation and with blsprice in one script, and compare the two with the standard error the script prints.
Monte Carlo in statisticsA value-at-risk figure that moves on every run is hard to defend in review. rng(seed) repeats a simulation exactly in RunMat, and each run keeps its script, seed and printed results.
Desktop appA European call by simulation, inside its standard error of blsprice.
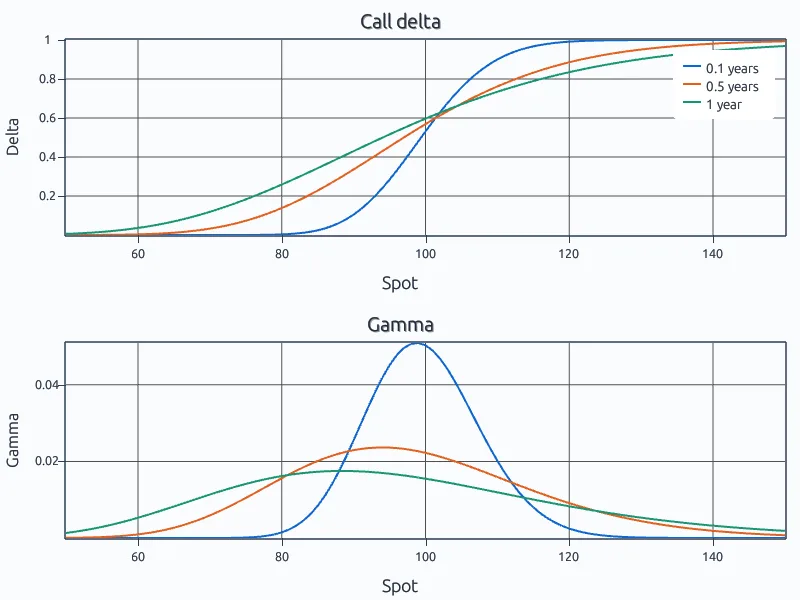
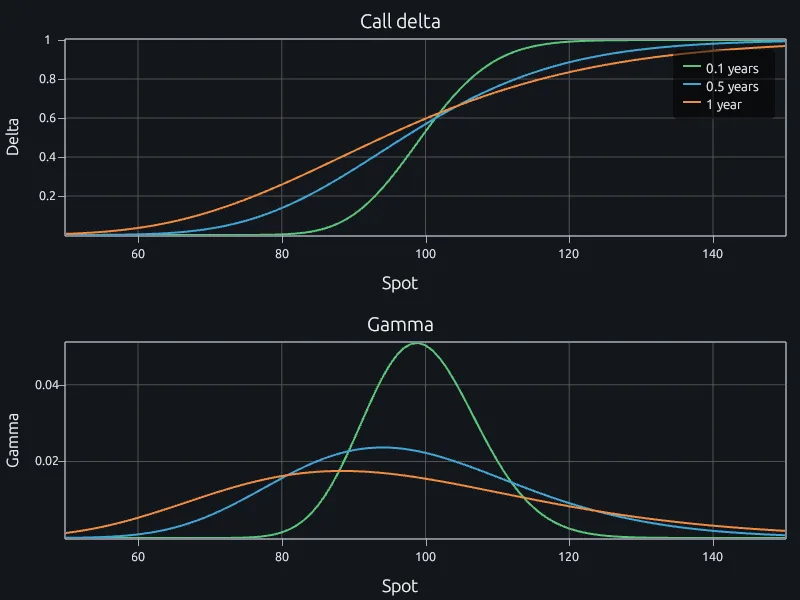
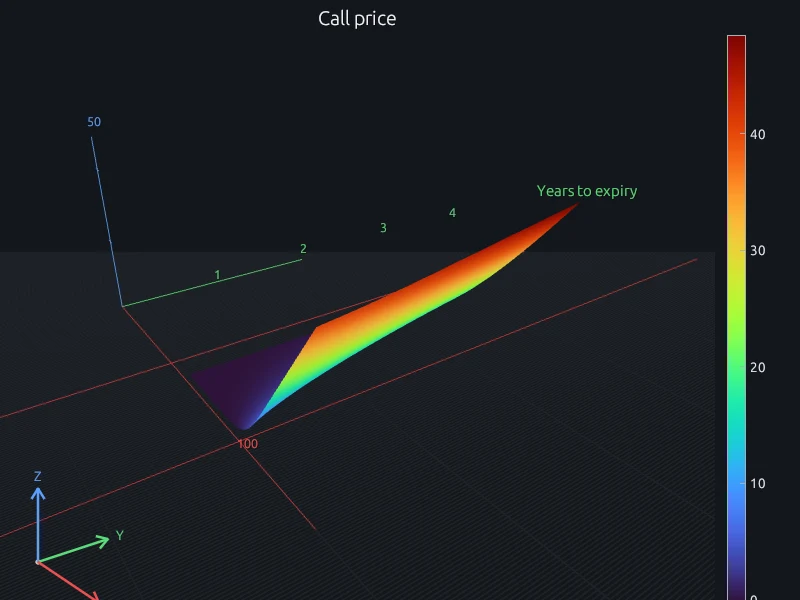
The option Greeks from the formulas, checked against blsprice.
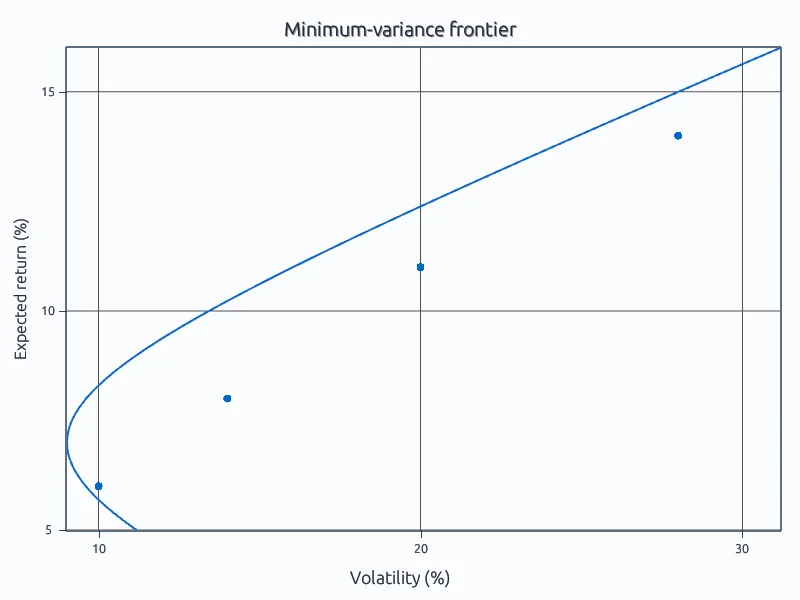
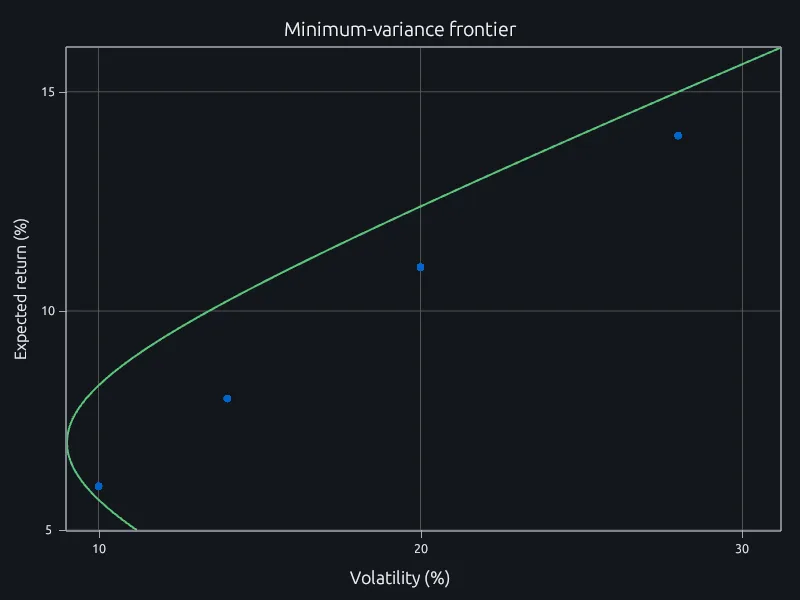
The minimum-variance frontier for four assets from their covariance.
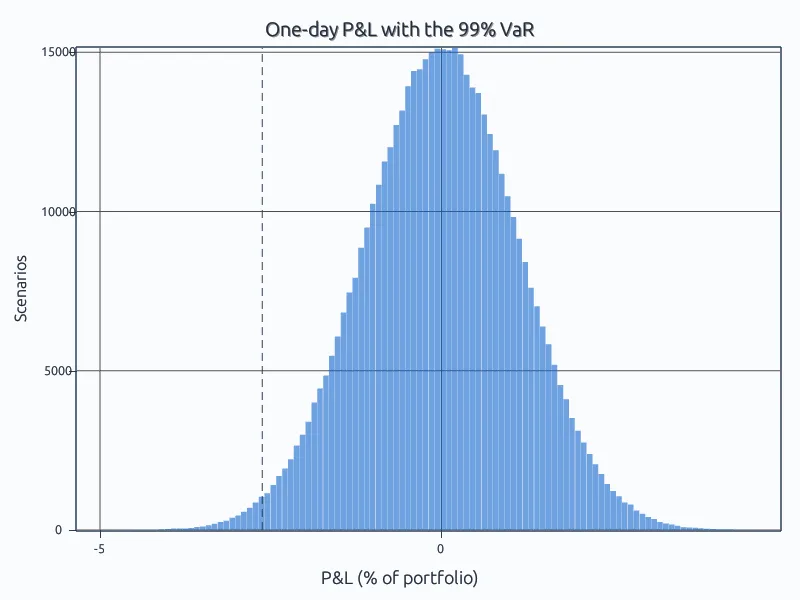
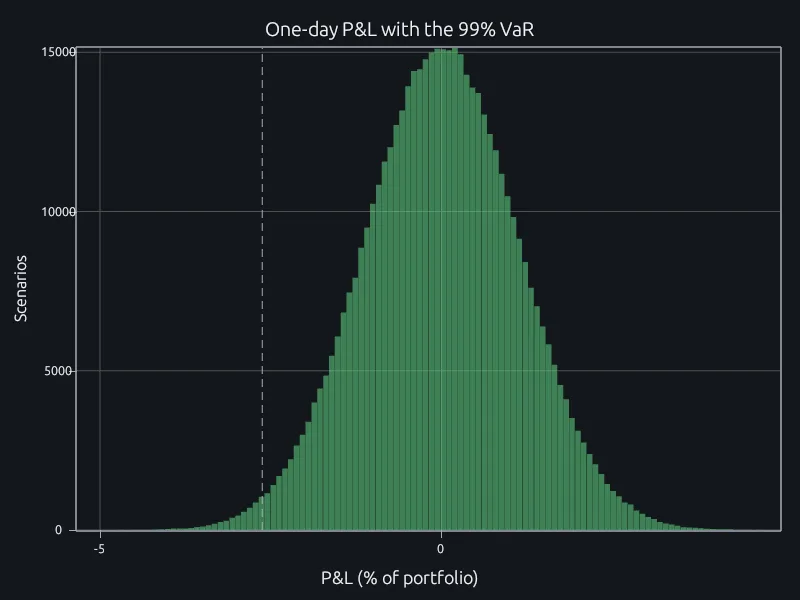
99% VaR and expected shortfall for three correlated assets.
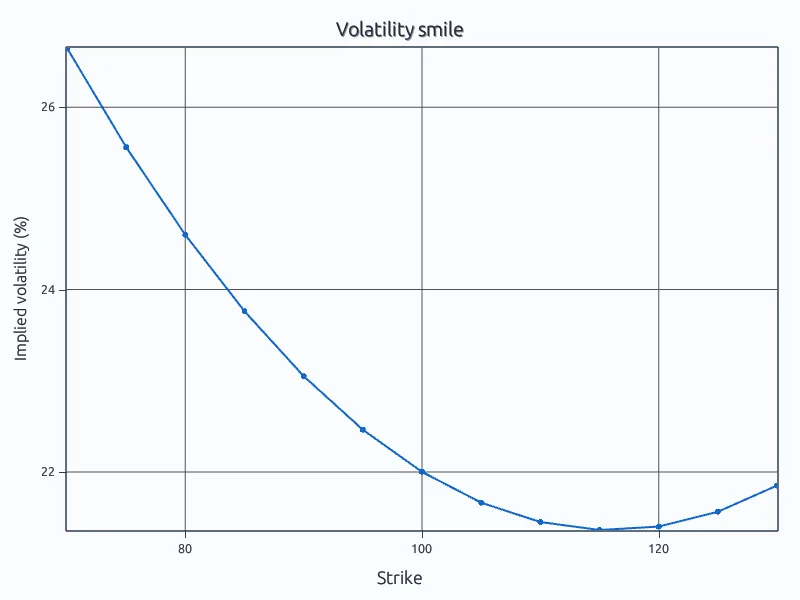
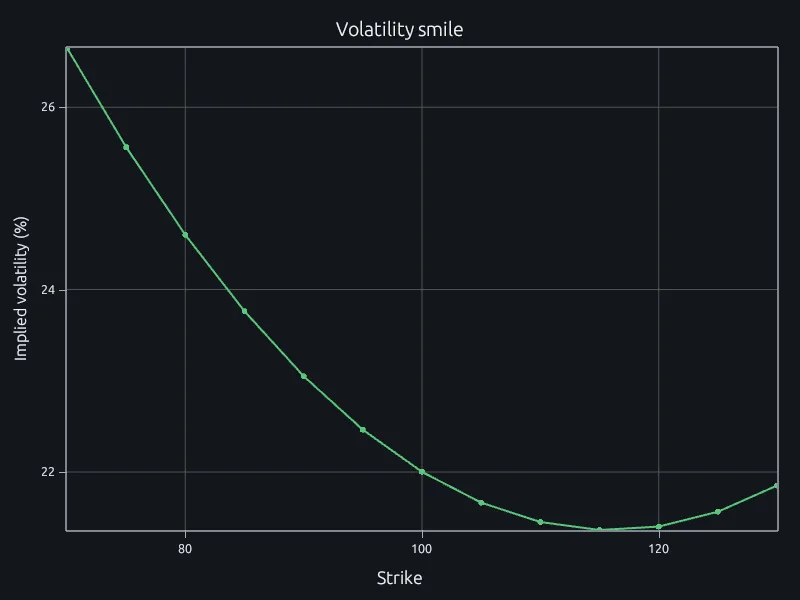
Volatility recovered from prices across 13 strikes with blsimpv.
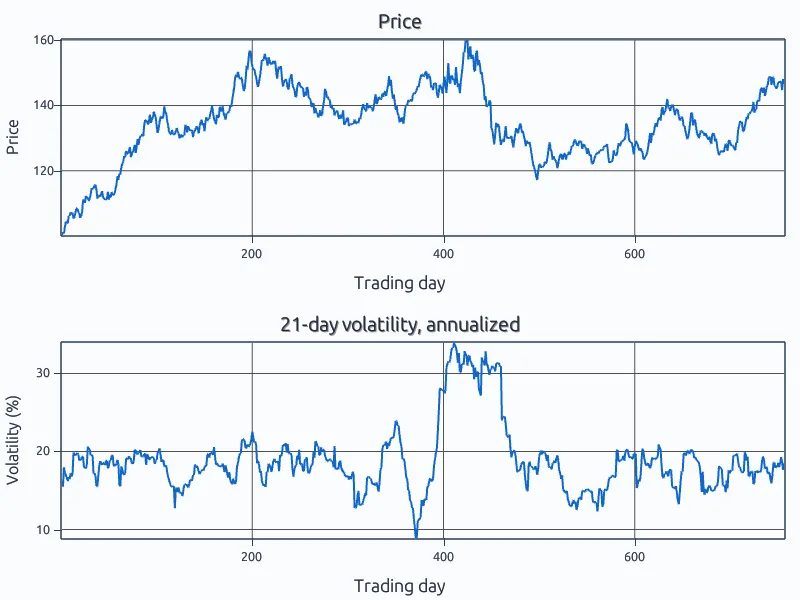
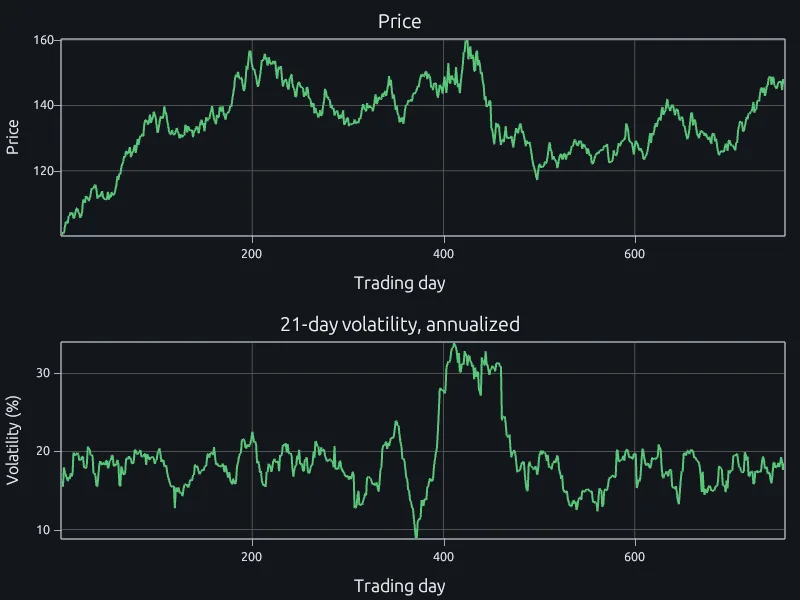
Maximum drawdown, rolling volatility and Sharpe ratio of a price series.